Get The Vehicle Or Equipment You Need & Keep Your Cash Working

Whether it’s a ute for the job, a truck for your fleet or new equipment for your business, asset finance helps you get the assets you need now and pay over time.

The asset itself secures the loan. That usually means sharper pricing than an unsecured loan, and your working capital stays free for wages, stock and growth.
CARS & UTES ✦
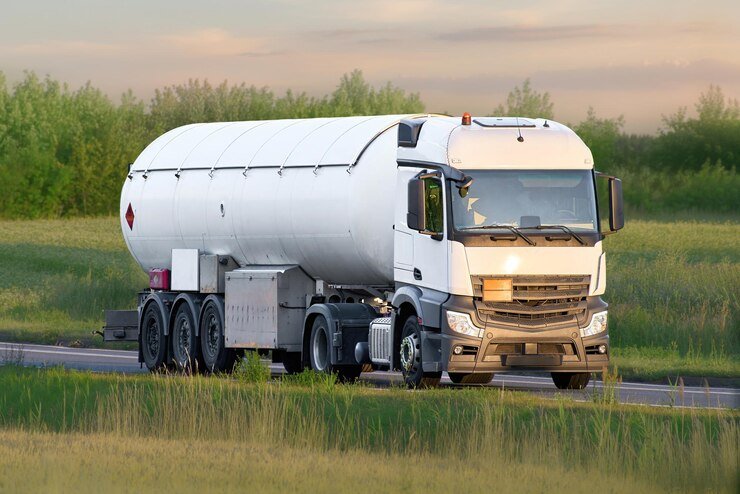
TRUCKS & TRAILERS ✦
CONSTRUCTION EQUIPMENT ✦
AGRICULTURAL MACHINERY ✦
MEDICAL EQUIPMENT ✦
IT & OFFICE EQUIPMENT ✦
HOSPITALITY EQUIPMENT ✦

What We Can Finance

Asset Finance For A Wide Range Of Industries

From commercial vehicles and construction machinery to medical, hospitality and office equipment, we help Australian businesses explore finance options for the assets they need to operate and grow.

01. Transport & Logistics

Prime Movers, Rigid Trucks, Trailers, Refrigerated Trucks, Tankers, Vans & Utes.

02. Construction & Trades

Utes, Vans, Tippers, Excavators, Skid Steers, Cranes & Tools.

03. Agriculture

Tractors, Harvesters, Sprayers, Balers & Irrigation Equipment.

04. Medical & Healthcare

Imaging Equipment, Dental Chairs, Practice Fit-outs & Specialist Equipment.

05. Hospitality & Retail

Commercial Kitchens, Coffee Machines, Refrigeration, POS Systems & Shop Fit-outs.

06. Office & IT

Computers, Servers, Phone Systems & Software Bundles.

Finance Structures

Explore Asset Finance Options That Suit Your Business

There are different ways to structure asset finance depending on your business needs, cash flow and how you plan to use the asset. We help you understand the options and explore a suitable solution.

01. Chattel Mortgage

OWNERSHIP FROM DAY ONE A popular option for businesses purchasing vehicles, machinery or equipment, with ownership generally held by the business from the start.

02. Hire Purchase

OWNERSHIP AFTER FINAL PAYMENT A finance option where you make regular payments towards the asset, with ownership transferring to you once all payments and obligations are completed.

03. Finance Lease

FLEXIBLE END-OF-TERM OPTIONS A structure where the lender purchases the asset and leases it to your business for an agreed period, with options at the end of the lease.
“Your accountant can confirm which structure suits your tax position. We’ll then find the lender and terms that fit.”
Chattel Mortgage Hire Purchase Finance Lease
Who owns the asset during the term You The lender The lender
When ownership passes to you From day one On the final payment Only if you pay out the residual at the end
End-of-term payment Optional balloon Optional balloon Residual value
How GST works Generally claimed on the purchase price Generally claimed on the purchase price Charged on each rental payment
Often suits Businesses that want to own the asset Businesses that want to own it once it's paid off Businesses that prefer to upgrade regularly

Refinance an Asset You Own

Put The Assets You Already Own To Work

There are two ways to refinance a business asset. You can move an existing loan to better terms, or you can borrow against equipment you already own outright to free up cash.

Sometimes called a sale and hire-back. A lender buys the asset from your business and hires it back to you. You keep using it and receive a lump sum to use in the business.

It can suit:

– A business that bought equipment with cash and now needs working capital.
– Funding a new contract, stock or expansion.
– Clearing a balloon payment that’s due.

It is not usually a fit for:

– Assets near the end of their working life, or with low resale value.

– Covering ongoing losses.

– Personal spending.

You may want to review your existing asset finance if:

– Your current repayments are high.

– A balloon payment is coming due.

– Your business is in a stronger financial position than when you first borrowed.

We’ll review the existing loan and consider whether refinancing could suit your situation. Any break costs or early payout charges should be checked before switching.

Ready to Explore Your Asset Finance Options?

Why Choose Ascentro Finance?

One Conversation, A Panel of Lenders

Go direct to a bank or a dealer and you see one set of options. We look across a panel of lenders to find the structure and terms that fit your business, and we handle the paperwork so you can keep working.
Choice

Access to a panel of lenders, including specialists in trucks, equipment and newer businesses.

Fewer knock-backs

We know which lenders suit which situations before an application goes in.

Plain English

Every cost, balloon and payout term explained before you sign.

Someone in your corner

One point of contact from first call to settlement, and we’re still here when your balloon or residual comes due.

How Asset Finance Works

A Simple Process From Enquiry To Settlement

We guide you through each stage of the asset finance process, helping you understand your options and what happens next.

Step 1

Tell Us About The Asset

Let us know what you are looking to purchase, its approximate cost and how it will be used in your business. A 15-minute call is usually enough to get started.

Step 2

Compare Your Options

We compare options across our lender panel, recommend a suitable structure and clearly outline the costs.

Step 3

Approval & Documentation

We prepare and lodge your application, keep you updated and walk you through the loan documents.

Step 4

Settlement & Delivery

Once finance is settled, the lender pays the seller and you can take delivery of your asset. We remain available throughout the life of your loan.

What It Costs You

We’re usually paid a commission by the lender when your loan settles. Some loans may also involve a fee from us. If so, we’ll tell you the amount in writing before you proceed. Full details are in our Credit Guide.

Documents You'll Need

Have These Documents Ready

Every lender is a little different, so we’ll confirm the exact list once we know your situation. Most applications need the following.

Driver’s licence or other photo ID.

Details of the asset: quote, invoice or dealer contract, or the seller’s details for a private sale.

A summary of your assets and liabilities, such as property, other loans and credit cards.

Two recent payslips.

Recent bank statements showing your salary.

ABN and GST registration details.

Recent tax returns and notices of assessment, or recent BAS and bank statements for a low-doc option.

Company or trust name, ABN and ACN.

Photo ID for each director or trustee.

Trust deed, for trusts.

Recent financial statements and tax returns, or BAS and business bank statements for a low-doc option.

Flexible Purchase Options

Finance Options For New And Used Business Assets

Whether you’re purchasing brand-new equipment or choosing quality pre-owned assets, we help you explore finance options that align with your business requirements and purchase plans.

New Asset Finance

Looking to purchase new vehicles, machinery or commercial equipment? Explore finance options for your next business investment.

Used Asset Finance

Considering pre-owned equipment? Explore finance possibilities for used vehicles and machinery, subject to lender requirements.

Dealer Purchase

Buying your business asset through an equipment dealer? We can help you explore suitable finance options for your purchase.

Pvt Sale Purchase

Planning to purchase directly from a private seller? Discuss your requirements and explore potential finance options.
We can look at finance for new and used equipment, bought from a dealer, at auction or privately. Some lenders limit the age of the asset at the end of the term, so tell us the year and condition up front.

Ready to Finance Your Next Business Asset?

Whether you’re purchasing a vehicle, upgrading machinery or investing in new business equipment, Ascentro Finance can help you explore suitable finance options for your business.

Got Questions ?

Frequently Asked Questions About Asset Finance

Not always. Many lenders will finance the full purchase price for established businesses with good credit. A deposit or trade-in can lower your repayments and help with approval.
Yes, many lenders finance private sales. They’ll usually check the asset is free of existing finance and may want an inspection or valuation. We’ll guide you through it.
Some lenders allow this, with extra checks to confirm the price is fair. Tell us up front so we can approach the right lenders.
It depends on the structure. With a chattel mortgage or hire purchase, GST-registered businesses can generally claim it on the purchase price. With a finance lease, GST is charged on each rental. Your accountant can confirm what applies to you.
A lump sum due at the end of the term. It lowers your regular repayments but increases the total interest. When it falls due, you can pay it, refinance it or trade the asset in.
Usually, yes. Most asset loans have fixed rates, so early payout may involve a break cost or the remaining interest. We’ll explain the payout terms before you sign.
You still owe the loan balance. That’s why lenders require comprehensive insurance. For vehicles, gap insurance can cover the difference between the insurance payout and the amount owed. Talk to your insurer about whether it suits you.
Yes. Directors or trustees are usually asked to provide a personal guarantee.

Options narrow when an ABN is under two years old, but they exist, especially with a deposit, property ownership or industry experience. Ask us.

Each credit enquiry is recorded on your file. That’s one reason to use a broker: we work out which lender is likely to approve you before an application is lodged.

Tell Us What You're Buying

Assets

Disclaimer

Ascentro Finance Pty Ltd is a Credit Representative (CRN 571173) of Finsure Finance & Insurance Pty Ltd (ACL 384704). The information on this website is general in nature and does not take into account your objectives, financial situation or needs. Before acting on it, consider whether it is appropriate for you. All applications are subject to lender credit criteria; terms, conditions, fees and charges apply. Ascentro Finance does not provide tax or accounting advice. Please speak with your accountant or tax adviser about the tax treatment of any finance structure. Novated Lease Additional Statement Novated leases are consumer credit. We’ll assess whether a lease is not unsuitable for your requirements and objectives before recommending it.